'We are very watchful about inflation and growth. But the main challenge is economic revival and growth.'
If banks cannot charge interest from borrowers during the moratorium, who will bear that cost? Should the depositors subsidise the borrowers by foregoing interest on deposits? In that case, we will turn banking on its head! notes Tamal Bandyopadhyay.
In yet another move to close the regulatory gap between banks and shadow banks, the Reserve Bank of India (RBI) has mandated exposure limits to the non-banking finance companies, in line with commercial banks. In the large exposure framework released on Tuesday, the regulator capped aggregrate exposure of NBFCs which are in the upper layer toward one entity at 20 per cent of capital base. The limit can only be extended by another 5% with board's approval. For a particular borrower group, the cap is at 25 per cent, with additional 10 per cent if exposure is towards infrastructure.

Lending on peer-to-peer platforms is fraught with higher risks but investors can earn as much as 12% to 36%.

Invest 5 to 10 per cent in a banking sector fund. Ensure that mutual fund's portfolio includes all three players -- private sector banks, public sector banks and NBFCs.
The first half of 2019-20 will be under pressure, since prices are expected to go up by Rs 7,000-8,000 at a time when sentiment is poor.

Most NBFCs will have to slow down their loan growth. Some of the most leveraged will have to sell a part of their assets (or loan book) to banks to raise incremental capital. Others may have to knock on the door of their deep-pocketed parents.

White labeled ATMs are set up by private non-bank companies that own and operate their own brand of ATMs.

SC wanted to know how it encashed securities deposited with RBI.
'In times of recovery, we may see a rural-urban divide with the urban pockets affected more by COVID-19, but the MFI business model should encourage banks to handhold them in this hour of crisis,' notes Tamal Bandyopadhyay.
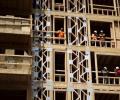
Many developers are facing financial challenges after the IL&FS defaults, after which non-banking finance companies - the major financiers to real estate firms - slowed disbursals.

'We have set out a timetable to reduce income tax rates for all incomes below Rs 50 lakh, and to progressively eliminate the surcharges on income above Rs 50 lakh, by 2024.' The Budget speech past CII president Naushad Forbes wants to hear.

Banks and insurers are beginning to reward customers who show exemplary conduct with lower prices and penalise those who behave poorly by imposing higher costs.

'India has about 22,000 tonnes of private gold, held by individuals and temples.' 'Much of this is locked up in safes and vaults as a dead investment. If we can put the vast reserves of gold to use, it would boost the economy,' says V P Nandakumar, executive chairman, Manappuram Finance, India's first listed gold loan company.
Attractions range from start-up challenges to non-monetary perks; employee stock options also play a role.
Is the worst over for Indian banks? The past two years saw them ride on treasury trades as deposits soared and credit growth dipped sharply. Gross and net non-performing assets (NPAs) moved south, and the provision coverage ratio (PCR), capital buffers, and profitability indicators are back at pre-pandemic levels. So, what's the plot ahead?
You can get a lumpsum sanctioned, but you may draw only part of it and pay interest on the amount used.
To invest $1 bn in realty sector, mulls new funds; has done exits worth Rs 8,000 crore, says founder
'There is no need to do anything, let your SIPs get deducted every month, and stick to your allocation between equity, fixed income and emergency funds and your risk covers.'
Though India was under lockdown for only seven days of the quarter, global demand and commodity prices began falling from February as COVID-19 was spreading in other countries. 1,002 listed companies - excluding banks, non-bank lenders, insurers, brokerages, and IT firms - reported a combined pre-tax loss of around Rs 2,700 crore during Q4.
The economy could grow at 6-6.5 per cent this fiscal year (2019-20 or FY20), said Chief Economic Advisor Krishnamurthy Subramanian, revising his earlier estimate of 7 per cent in the Economic Survey. In an interaction with Arup Roychoudhury, he said supply-side measures, including corporation tax cuts, will boost consumption and demand, and non-tax revenue may make up for shortfall in tax revenues.
Apart from streamlining loan processing, most public sector banks charge lower interest rate, an aspect which seems to be game changer.
L&T Finance CEO interview.
Crisil Ratings on Wednesday said a broad-based recovery is on for India Inc currently, and upgraded its credit quality outlook to 'positive' from the earlier 'cautiously optimistic'. The rating agency said the credit ratio, which illustrates the number of upgrades to downgrades, rose to over 2.5 times in the first four months of the fiscal, as compared to 1.33 times in the second half of FY21, it said in a statement. The rating agency said it has also done a study of 43 sectors, excluding the financial sector, accounting for 75 per cent of the overall Rs 36 lakh crore in outstanding debt, which shows that the current recovery is broad-based.
The Reserve Bank of India (RBI) on Wednesday proposed to make interoperability mandatory for digital payments firms. It also allowed users to withdraw cash from e-wallets and fintech companies to process RTGS and NEFT transactions. The RBI expressed dissatisfaction over prepaid payment instruments' (PPIs') failure to migrate towards full-KYC (know your customer) PPIs, and therefore interoperability, even two years after guidelines were issued.
The latest whistle-blower revelations of multiple shenanigans at global ride-hailing app Uber, coming thick and fast after serial exposes of various dodgy practices at Facebook, Apple, Amazon, Netflix, Google in the recent past raises uncomfortable questions about India Inc. If the FAANGs, Twitter and Uber can be guilty of multiple and diverse transgressions what's happening in Indian corporations? It can be nobody's case that India's largely family-owned and - managed private sector is a beacon of transparency or best corporate governance practices, bolstered as it is by an informal omerta among employees, managements and even boards.

One incident should not be used to generalise the health of all cooperative banks, says RBI governor Shaktikanta Das.
A host of dynamic reforms, policies and announcements during the last five years are expected to reach its logical fruition in the second term, says Ankit Kansal.

Here's what borrowers must pay attention to before going for such medical loans.
Renewable energy is mistakenly restricted to electricity.

The BJP still does not have a majority in Upper House of Parliament, the Rajya Sabha, and this will pose hurdles to the party's legislative reform agenda

These firms reported a combined operating profit of Rs 26,077 crore (Rs 260.77 billion).
It is easy to invest in exotic products but difficult to exit them. Think carefully before investing rather than being blown away by expected returns alone, suggests Mrin Agarwal, founder, Finsafe India.
Not all NPAs are treated as wilful defaulters.
Declining interest rates, a near-normal monsoon leading to higher rural incomes and pay hikes for central government employees are key triggers, says Dev Chatterjee.

With the RBI capping top managements' tenure at lenders, Kotak Mahindra Bank's head Uday Kotak on Monday said his current term as the managing director and chief executive is till December 2023 and the board will take a call on succession in due course. Kotak also stressed that the commitment to institution building has been a core value for the entity over the last 36 years of its existence. The RBI last week capped MD and CEOs' terms at private sector lenders at 15 years, from October 1 onwards, but has allowed the serving bank heads to complete their current appointments. Uday Kotak, who is also among the promoters of the lender, has been at the helm for over 17 years already.

NBFCs with a proven track record, supported by the brand values of reputed corporate, can play a key role in bringing the benefits of banking and economy to the underserved and newer segments of India.
The idea was that despite some defaults the high rates would assure good profits.

An internal working group set up by the RBI has proposed to raise the cap on promoters' stake in private banks from the current 15 per cent to 26 per cent in 15 years. The group has also recommended that large corporate or industrial houses may be allowed as promoters of banks only after amendments to the Banking Regulation Act and strengthening of the supervisory mechanism for conglomerates, including consolidated supervision. The Reserve Bank of India had constituted the internal working group (IWG) on June 12, 2020, to review extant ownership guidelines and corporate structure for Indian private sector banks.
Given Indian corporates's high indebtedness, new credit will be used for servicing loans rather than building factories. This is setting us up for more companies on life support and more zombie banks, warns Rahul Jacob.
